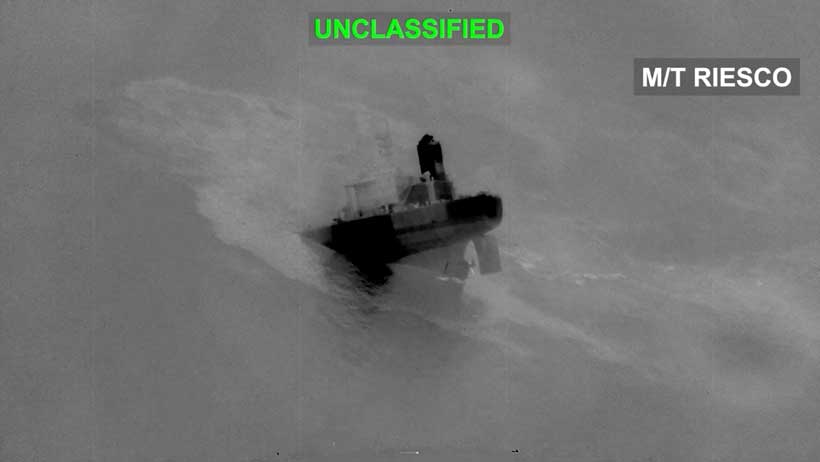
The conflict is rewriting the traditional geopolitical playbook. Usually, military escalation triggers a flight to safety and central bank easing; here, the war acts as a direct inflationary shock through the fuel pump. This forces a hawkish response from the Fed, even as the administration remains deeply entangled in the regional standoff. President Trump’s vague response regarding Washington’s involvement in the recent attack on an Iranian vessel near Hormuz underscores the political sensitivity of the situation, particularly as he pressures Ukraine to halt refinery strikes to prevent further diesel price spikes.
This dynamic creates a sharp divergence in economic outcomes. Saudi Arabia and the UAE secure windfall revenues, yet they face increasing vulnerability as regional security architectures fray, evidenced by the weekend seizure of Yemen’s Red Sea coast by Ansarullah forces. Conversely, oil-importing nations like India and Turkey are suffering under the combined burden of expensive crude and a strengthening dollar. While the DXY index at 99.46 suggests investors still view the dollar as a primary safe haven, the Fed’s upcoming decision will reveal whether policymakers view this energy inflation as a structural constraint or a temporary disruption. A rate hike would signal that the central bank considers war-driven energy costs to be the primary threat to the domestic economy, effectively tethering US monetary policy to the volatile reality of the Gulf.

Comments (0)
No comments yet. Be the first!