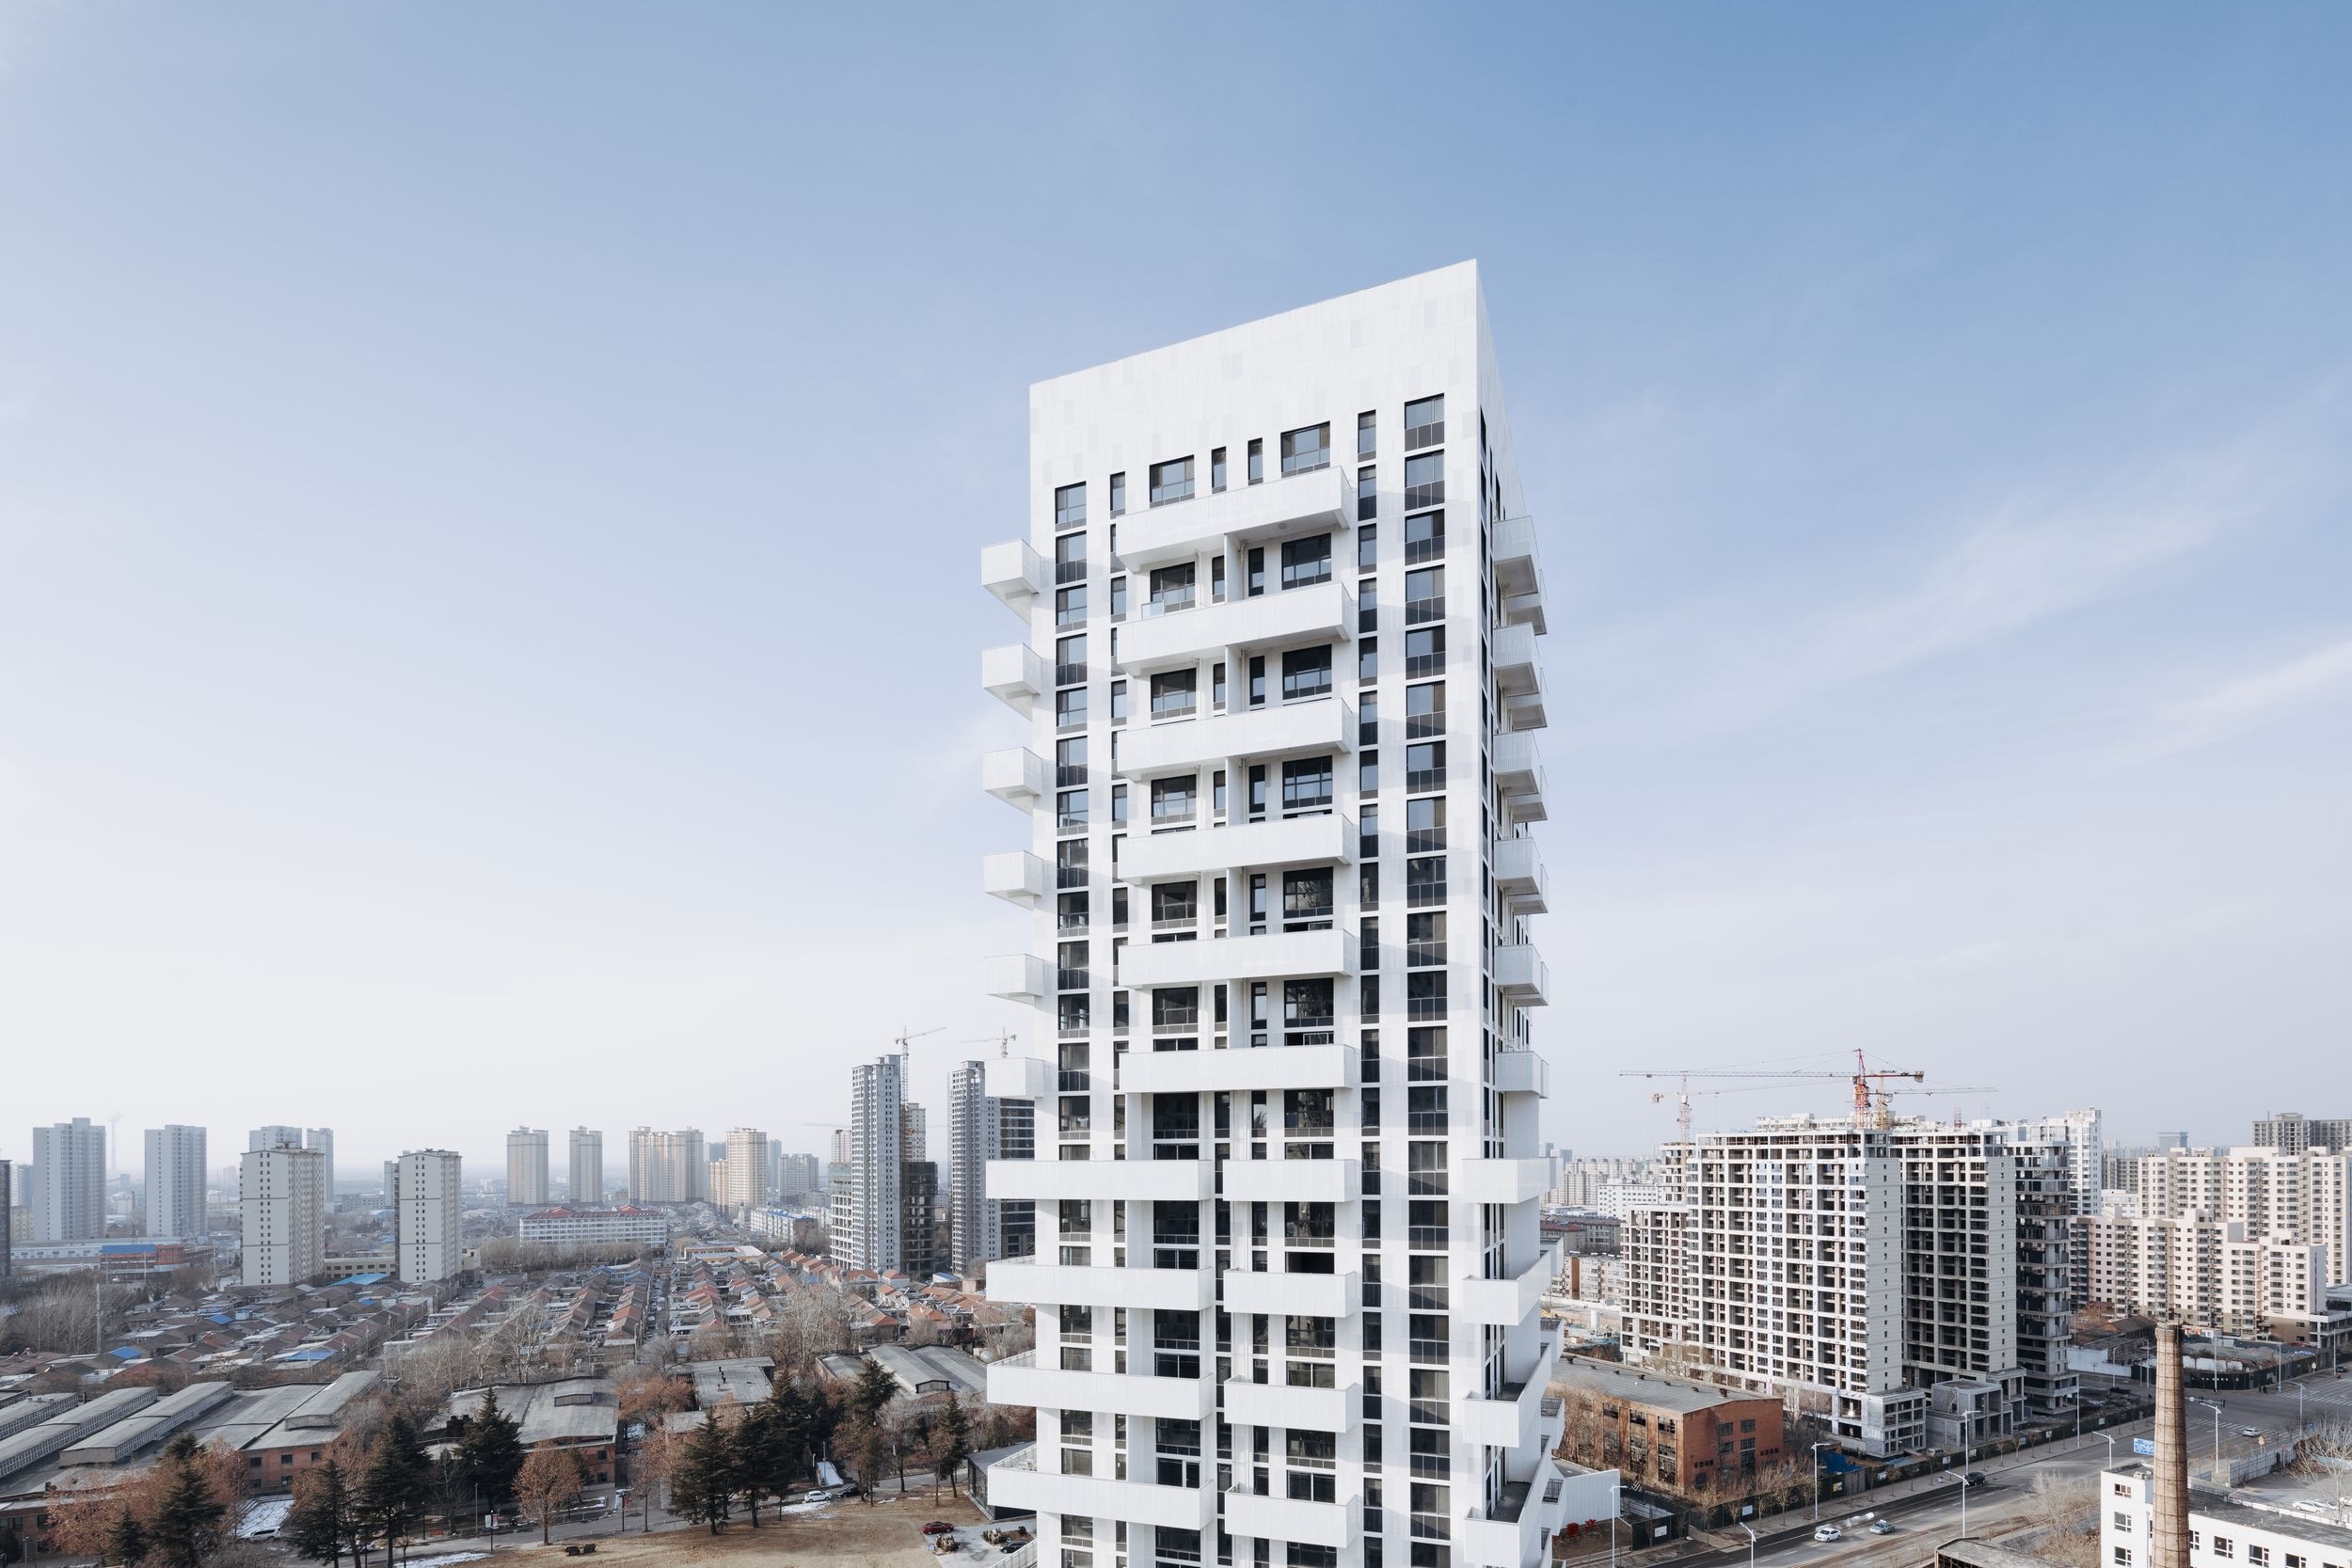
The divide between market homeowners, legacy residents, and renters has created a paradox where vast housing wealth fails to translate into fluid economic activity. Estelle Xue Liu and Jibingxin Han identify three distinct urban groups, noting that while market-rate homeowners grew to 122.9 million by 2020, over 107 million households remain in legacy housing—properties often lacking basic amenities like modern plumbing or elevators. Because these assets are difficult to sell or use as collateral, they function more as a trap than a financial safety net.
This lack of liquidity forces households to adopt cautious spending patterns. When income fluctuates, legacy homeowners struggle to maintain discretionary consumption because their wealth is locked in non-tradable property. Meanwhile, market homeowners often find their budgets squeezed by mortgage obligations, and renters divert potential spending into aggressive down-payment savings. The research highlights that the post-2021 downturn has exacerbated these issues, as reduced expectations of future price gains dampen consumer confidence.
Policy solutions must move beyond simple construction targets. Future stability likely depends on urban renewal, energy-efficiency upgrades, and mechanisms that allow households to monetize existing assets. By shifting focus from building new square footage to improving the quality and accessibility of existing stock, planners might finally address the persistent gap between national housing abundance and individual financial flexibility.


Comments (0)
No comments yet. Be the first!