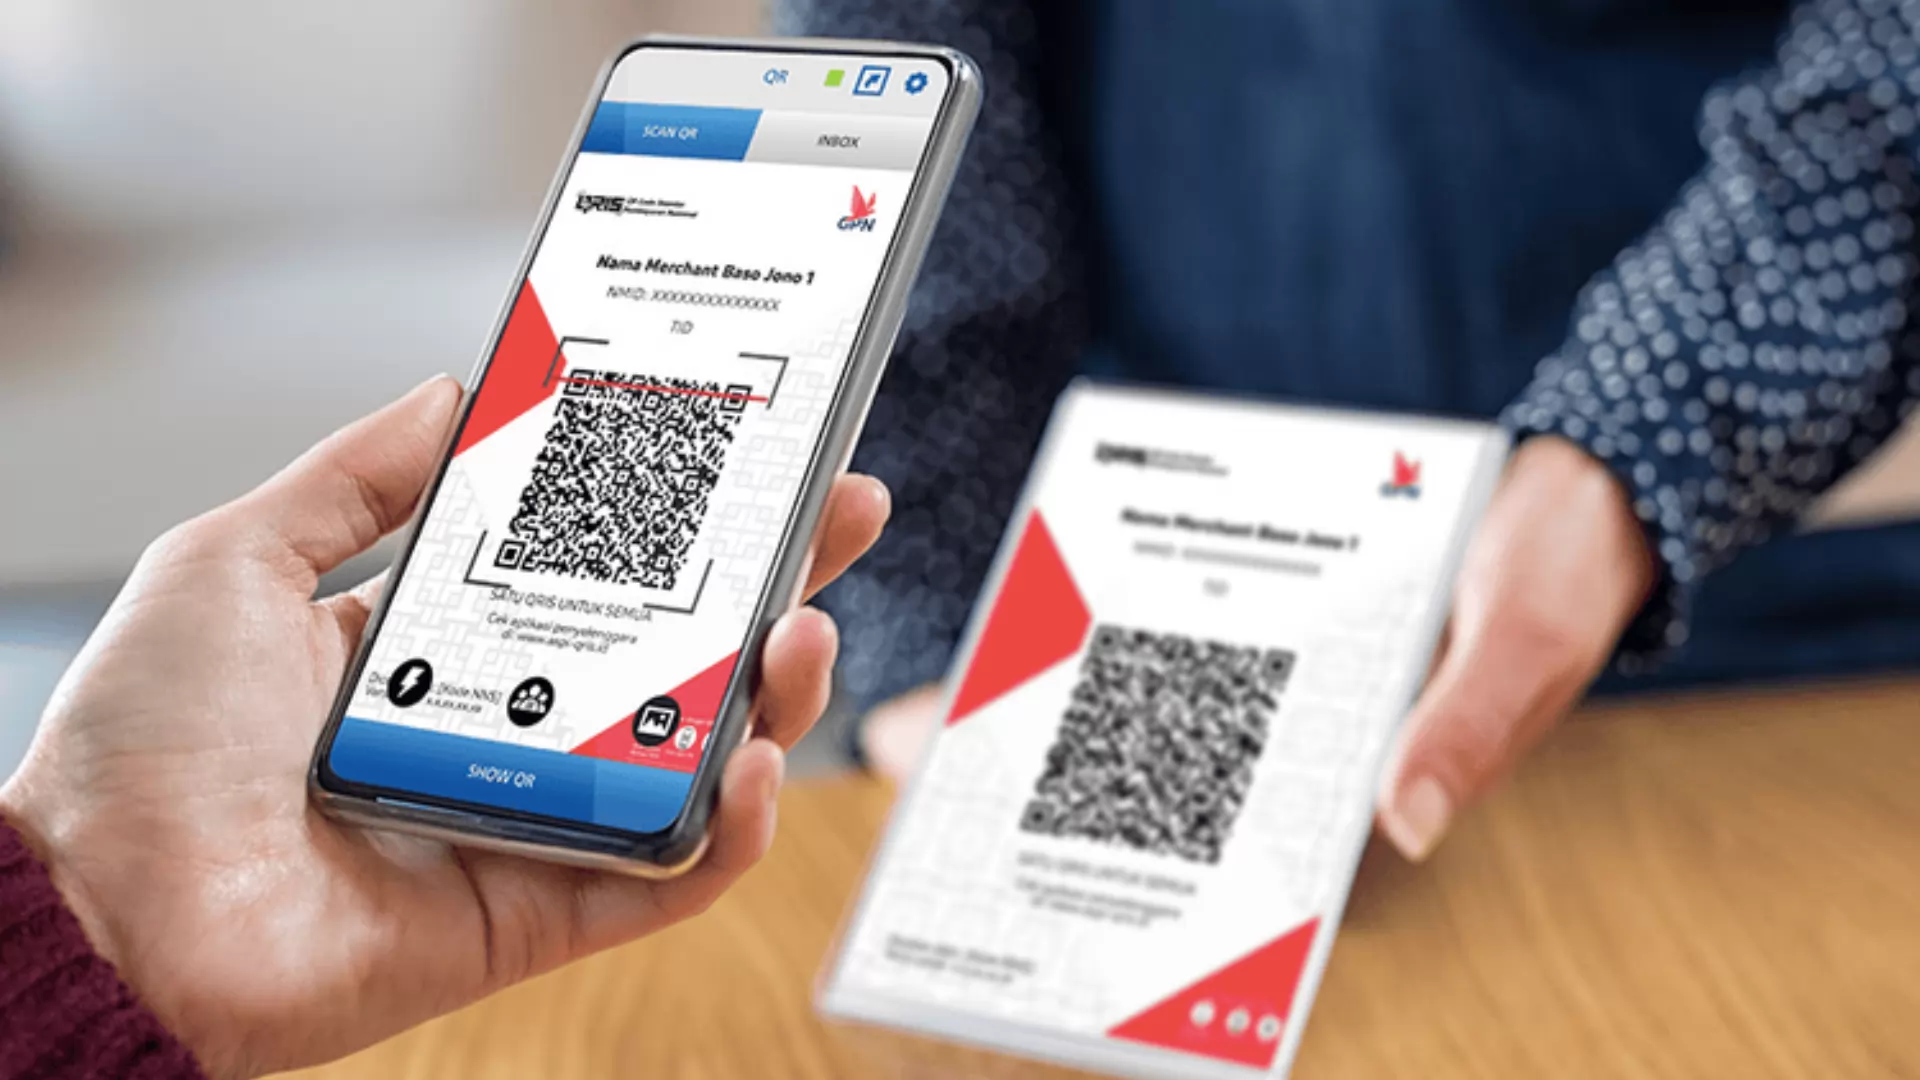
Bank Indonesia’s October 2026 announcement to leverage QRIS transaction data marks a shift toward algorithm-based lending for micro, small, and medium-sized enterprises (MSMEs). With nearly 50 million merchants already using the standard, the policy seeks to replace rigid collateral requirements with digital footprints. This attempt at financial inclusion follows a period of regional unrest, where economic dissatisfaction in nations from Nepal to Morocco highlighted the fragility of public trust when growth fails to reach the grassroots level.
However, digitizing credit carries inherent risks. A 2015 synthesis of microcredit studies suggests that loan access does not inherently guarantee wealth creation. Without broader support—such as improved infrastructure, stable electricity, and technical skills—easier debt might trap vulnerable vendors in repayment cycles rather than fueling business expansion. The challenge is compounded by Indonesia's evolving regulatory landscape. While the Personal Data Protection Law provides a framework for data rights, the lack of a fully operational supervisory body leaves significant questions regarding how merchant data will be protected, contested, or shared between institutions.
Success depends on moving beyond simple transaction volume as a proxy for viability. If authorities prioritize transparent, portable data and focus on business outcomes rather than just loan disbursement, the model could serve as a genuine ladder for growth. If not, digital credit risks becoming a new sorting mechanism that favors those already plugged into the system, further widening the divide between the connected and the excluded.

Comments (0)
No comments yet. Be the first!